 by
The Spring Was Not a Fair Fight
You did everything right. Pre-approved. Polished offer. Over asking.
And you still lost the house to someone who paid cash and waived the inspection on a 1920s stone colonial.
If that happened to you in Wyomissing, Shillington, West Reading or anywhere across Berks County this year, you were not outplayed. You were simply bidding in a market that rewarded recklessness over readiness.
That market is changing. And the buyers who understand how will be negotiating from a very different chair this winter.
What Has Shifted in the Berks County Housing Market
Let’s be precise, because precision is where leverage lives.
Berks County is still a desirable place to own a home. The well-priced homes still move quickly. In September 2026, the county’s median sale price was about $306,750, up roughly 2.9% from last year, with homes selling in around 9 days. But active inventory climbed about 12.8% year over year to roughly 590 listings, according to Coldwell Banker Hearthside’s September report.
More choice means more room to negotiate. And the national picture is moving faster than our local one:
- Redfin counted 58% more sellers than buyers nationally in August.
- More than 45% of U.S. home sales in September included a seller concession.
- Freddie Mac’s 30-year average sat at 7.18% on November 5, well above this year’s low of 6.09%.
Higher rates thinned the crowd. The buyers who remain are serious, and sellers know it. That is precisely the moment to ask for something most buyers never think to request.
Why a Seller-Funded Rate Buydown Belongs in Your Offer Now
A rate buydown is money the seller contributes at closing to reduce your mortgage interest rate. The most common structure is the 2-1 buydown: your rate is 2% lower in year one, 1% lower in year two, then returns to the full note rate in year three.
Here is what that looks like on a home near the recent Berks County median:
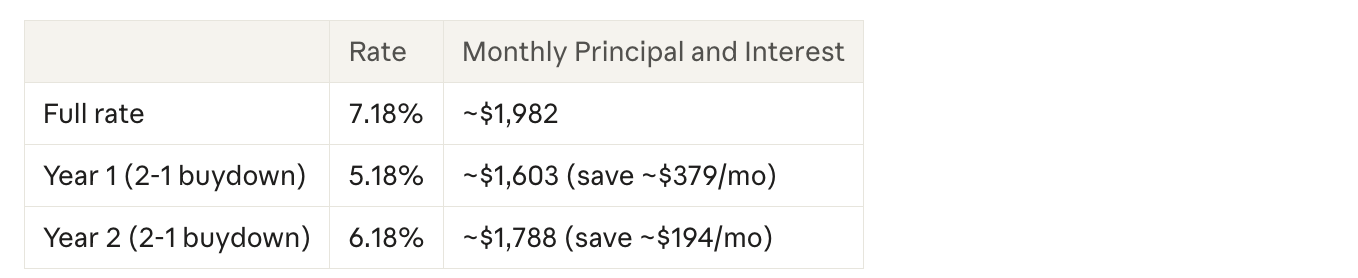
The above chart is just an illustration: $325,000 purchase, 10% down, $292,500 loan, 30-year fixed. Your lender’s figures will vary.
Prefer a quick video on how to negotiate for a home more strategically?
The cost to fund that buydown is roughly $6,900. Now compare it to the alternative most buyers ask for. A $10,000 price reduction on the same home lowers your payment by only about $61 a month.
Same seller. Smaller check. Dramatically more impact on your monthly budget.
There is also a permanent buydown, where the seller pays discount points to lower your rate for the life of the loan. Pricing varies by lender, so ask yours to quote both before you write the offer.
And if rates fall in the next year or two, you may be able to refinance. The buydown simply gives you breathing room in the meantime.
Four Sophisticated Negotiation Strategies for Berks County Home Buyers:
- Pay the Price. Negotiate the Payment.
Sellers are protective of their sale price. It is the number their neighbors see and the number future appraisals lean on.
So give them the price, or something close to it, and ask for a concession directed toward a rate buydown. The seller keeps a clean headline number. You keep a lower monthly payment. Both parties leave the table with their priorities intact.This is the single most effective structure in today’s market, and it is the one cash buyers cannot replicate.
- Read the Listing’s Clock
Every listing tells a story through its timeline. A home that has been on the market for three weeks or longer, has had a price reduction, or sits vacant is carrying costs every month it remains unsold.
That is leverage. Use it with discretion.Before writing an offer, your agent should be asking the listing agent the right questions. What is the seller’s ideal closing date? Have they already purchased their next home? Has anyone else shown serious interest? The answers shape how much you ask for and how you frame it. The late fall and holiday season adds pressure of its own. Fewer buyers are touring, and sellers who listed in September are reassessing.
- Turn Inspection Findings Into Rate Relief
The spring trained buyers to waive inspections. Please do not carry that habit into winter, particularly on a historic home. Restore the inspection contingency, then use what it uncovers strategically. Rather than asking the seller to coordinate repairs, request a credit at closing. That credit can be applied toward your closing costs or your buydown, within your loan program’s limits. The seller avoids managing contractors. You gain control over who does the work, and you convert a dated furnace or a tired roof into a lower monthly payment. - Trade Time for Money
Cash buyers often win on speed. You can win on flexibility.
If a seller needs a specific closing date, or a few extra weeks in the home after settlement through a short rent-back, offer it. Time is currency to a seller juggling their own move. Exchange it for the concession you actually want.
The most strategic offers are not the loudest. They simply give each side what it values most.
Know the Limits Before You Ask
Seller contributions are capped by your loan program, not by the seller’s generosity. Generally:
- Conventional, less than 10% down: up to 3% of the price
- Conventional, 10% to 24.99% down: up to 6%
- Conventional, 25% or more down: up to 9%
- FHA: up to 6%
Concessions cannot be used toward your down payment or reserves, and they cannot exceed your actual allowable costs. Confirm your exact cap with your lender before you write the offer, so every dollar you negotiate can actually be used.
Frequently Asked Questions by Buyers in Berks County
Is Berks County a buyer’s market right now?
Not entirely. Well-priced homes still sell quickly. But rising inventory and higher rates have given prepared buyers meaningfully more negotiating room than they had in the spring.
What is a seller-paid rate buydown?
It is a seller concession used to lower your mortgage interest rate, either temporarily (such as a 2-1 buydown) or permanently through discount points.
Is a rate buydown better than a price reduction?
Often, yes, for your monthly payment. In the example above, a roughly $6,900 buydown saves about $379 a month in year one, while a $10,000 price cut saves about $61 a month.
How much can a seller contribute in Pennsylvania?
The limits are set by loan type nationally, not by the state. Conventional loans allow 3% to 9% depending on your down payment, and FHA allows up to 6%.
The Buyers Who Win This Winter
The spring rewarded whoever was willing to take the most risk. This season rewards whoever arrives with the most strategy.
If you lost a home in the past six months, you did not lose your opportunity. You were simply early. Now the leverage has shifted, and the buyers who understand how to use it will secure not just a house, but a position.
Contact me if you want to get the conversation started! And don’t forget to follow along on Instagram for design inspo and life in 610.
Disclosure: This article is for general information and is not lending or legal advice. Rates, limits and payment figures are illustrative; confirm all numbers with your lender.